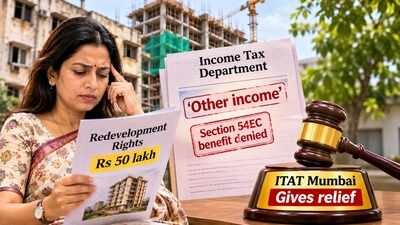
You give your property for redevelopment and get payment in lieu which you then reinvest to claim capital gains exemption. The Income Tax Department, however, classifies it as ‘income from other sources’ and adds it to your total income. What do you do?In one such case, the Mumbai bench of the Income Tax Appellate Tribunal (ITAT) has ruled in favour of the taxpayer, holding that the payment was consideration for granting development rights in the property and was therefore taxable under the head “Capital Gains”, rather than “Income from Other Sources”.
What the case is about
A Mumbai woman received Rs 50 lakh from a property developer under a redevelopment agreement. She then invested the amount in Rural Electrification Corporation (REC) bonds to claim income tax exemption.However, the Income Tax Department treated the receipt as “Income from Other Sources” instead of capital gains, and denied her the benefit of the exemption claimed under Section 54EC of the Income Tax Act, 1961.She had filed her income tax return for assessment year 2011-12, declaring a total income of Rs 2,64,260. The return disclosed capital gains of Rs 99,060 and she claimed an exemption under Section 54EC for investment in REC bonds.The assessment was reopened in 2018 after the Assessing Officer formed the view that income chargeable to tax had escaped assessment. Following a notice under Section 148, the woman filed another return on July 14, 2018, declaring the same income.During reassessment, the officer examined a development agreement dated August 2, 2010, entered into for redevelopment of a property.According to the agreement, the owners had agreed to allow the developer to redevelop the existing building by demolishing the structure and constructing a new one. The arrangement involved 16 family members or owners, four tenants and two additional claimants on one side, and the developer on the other.The agreement provided for aggregate monetary consideration of Rs 2 crore to the owners belonging to four groups.The woman received Rs 50 lakh as her group’s share. The owners also retained the floor space index (FSI) required to construct a total carpet area of 6,400 sq ft for their residential occupation, while the remaining development potential was to be used by the developer.The woman’s position was that the payment represented consideration for granting development rights, which constituted a capital asset. She maintained that the amount had been invested in REC bonds and that the exemption under Section 54EC was therefore available.The Assessing Officer accepted that the agreement was for development and not for sale of the property. He also held that Section 50C, which deals with stamp-duty value in certain transfers of land or buildings, did not apply because the transaction did not involve a sale of the land or building itself.However, the officer took the view that the Rs 50 lakh could not be assessed as capital gains. He reasoned that the owners retained their rights in the property and would receive premises in the redeveloped building. Since the payment was non-refundable and the underlying property remained with the owners, he treated the receipt as income from other sources.The officer accordingly added Rs 50 lakh to the woman’s income, taking it to Rs 52,64,260, and initiated penalty proceedings. The Commissioner of Income Tax (Appeals) upheld the addition and denied the Section 54EC exemption.She then challenged the decision before the tribunal. During the pendency of the appeal, she died in early 2026. Her daughter was brought on record as her legal representative after the tribunal considered the death certificate, an affidavit and the no-objection from the other legal heir.The tribunal set aside the lower authorities’ decisions on the classification of the Rs 50 lakh receipt and directed the Assessing Officer to assess it under capital gains and allow the Section 54EC exemption in accordance with the law, subject to verification of the statutory conditions.
Why the court ruled in favour of property owner
ITAT Mumbai ruled that development rights qualify as a capital asset. Since the payment was made in exchange for transferring valuable rights linked to immovable property, it was liable to be taxed as capital gains.The tribunal further observed that once the receipt is classified under ‘capital gains’, the taxpayer’s claim for an exemption under Section 54EC cannot be rejected simply because the income tax officer had assessed it under the wrong head of income.The tribunal focused on the nature of the rights for which the developer had paid the Rs 50 lakh. It found that the payment was not an independent or gratuitous receipt but arose directly from the contractual arrangement under which development rights were granted.The order stated: “The consideration was therefore intrinsically connected with the rights parted with by the assessee and other owners in favour of the developer.”The tribunal held that development rights in immovable property are valuable rights and form part of the bundle of rights attached to ownership. Their transfer can constitute the transfer of a capital asset even when the owners do not sell the entire land or building.The tribunal explained: “However, from this finding, it does not follow that there was no transfer of any capital asset at all.”The fact that Section 50C did not apply was also not decisive. The tribunal noted that the absence of a sale of land or building did not mean that no capital asset had been transferred. The grant of development rights itself had to be considered for tax purposes.The tribunal also disagreed with the reliance placed by the lower authorities on the developer’s accounting treatment. The developer had treated the payment as revenue expenditure in its books, but the tribunal held that this could not determine how the receipt should be classified in the hands of the recipient.As the order stated: “The taxability of a receipt in the hands of the recipient has to be determined with reference to the nature of the right transferred by the recipient and not on the basis of the accounting treatment adopted by the payer.”The tribunal directed the Income Tax Department to examine whether the taxpayer had fulfilled the requirements of Section 54EC and grant the exemption if the prescribed conditions were met. Under this provision, the capital gains must be invested in eligible bonds within six months of the transfer of the property or development rights.The exemption is capped at Rs 50 lakh, and the bonds must be retained for the prescribed lock-in period, which is currently five years, compared with three years earlier.
What it means for property owners
The ruling has implications for property owners involved in redevelopment. ITAT Mumbai has clarified that payments received for transferring development rights must be taxed under the head ‘capital gains’ rather than ‘income from other sources’.The tribunal has also held that taxpayers can claim an exemption under Section 54EC of the Income-Tax (I-T) Act by investing the capital gains in notified bonds, provided they meet the prescribed statutory conditions. Such an investment can lower the amount of capital gains subject to tax.The decision comes at a time when redevelopment is reshaping large parts of Mumbai and its surrounding suburbs. Thousands of residents living in ageing cooperative housing societies are signing agreements with developers, often in exchange for a mix of larger homes, cash compensation, corpus funds and other benefits.