
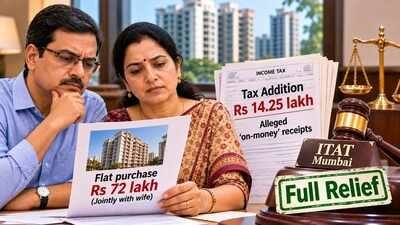
When you buy a property, it is very important to keep all records of transactions and payments. In case of an Income Tax Department query, documents form an important part of your defence.The Income Tax Appellate Tribunal (ITAT), Mumbai, has deleted a Rs 14.25 lakh addition made against a Thane flat buyer after the Income Tax Department alleged that he had paid money over and above the consideration recorded in the property agreement.The tribunal observed that the Income Tax Department had failed to establish any link between the buyer and the alleged ‘on-money’ transaction. Read on to know what happened.
What the case is about
The dispute involved a man who purchased a flat in Thane, jointly with his wife for Rs 72 lakh. The property was registered in April 2012.The man filed his income tax return for assessment year 2012-13, declaring income of Rs 2,71,280. The return was initially accepted, but the assessment was subsequently reopened after the department received information concerning alleged cash payments to the real estate developer from whom the flat had been bought.According to the assessing officer, material associated with the group’s Gmail and Yahoo accounts contained details of alleged ‘on-money’ receipts.The officer also referred to an Excel sheet said to contain flat-wise and shop-wise details of cash payments. Statements by the group’s sales head, and one of its promoters, were also cited.On this basis, the officer alleged that the man in this case had paid additional cash for the flat.Acting on information shared by the investigation wing, the assessing officer alleged that the taxpayer had paid Rs 28.5 lakh in cash during the financial year 2011-12.Since he held a 50% share in the property, the officer treated Rs 14.25 lakh as unexplained money and added the amount to his taxable income, making it liable to tax at a steep rate.The man disputed the allegation. His representative submitted that he and his wife had purchased the flat for Rs 72 lakh and that the payments were reflected in the transaction records and registered agreement dated April 4, 2012. The taxpayer also produced a confirmation from the builder acknowledging receipt of Rs 72 lakh.The taxpayer argued that the department had not supplied the material allegedly establishing the cash payment.He also challenged the use of third-party statements without an opportunity to cross-examine the people who made them.The Commissioner of Income Tax (Appeals) upheld the addition and declined his request for cross-examination, prompting the appeal before the tribunal.
Why ITAT Mumbai ruled in favour of property buyer
Mumbai ITAT bench found that the Rs 14.25 lakh addition to the taxpayer’s income was based largely on statements recorded from the developer’s officials and references to electronic material purportedly seized during the search.The bench pointed out that the alleged incriminating documents had neither been submitted as part of the case records nor provided to the taxpayer. It also noted that the Gmail and Yahoo mail records cited by the Income Tax Department were not produced during the assessment proceedings.The order states: “Copy of incriminating material or the material contained in the alleged Gmail or yahoo mail is neither brought on record no supplied to the assessee.”The tribunal observed that the taxpayer had denied paying any cash over and above the declared price and had submitted a confirmation from the builder acknowledging receipt of Rs 72 lakh for the flat.The tribunal also noted that the lower authorities had not taken account of the builder’s confirmation acknowledging receipt of Rs 72 lakh. It observed: “No cognizance of confirmation of builder was taken by AO or the ld CIT(A).”Cross-examination was another central issue. The man had challenged the use of statements made by third parties without being allowed to question them. The tribunal stated: “Statement per se cannot be considered as evidence, against third party unless it is tested by cross examination.”The tribunal also considered earlier ITAT decisions involving similar additions against buyers of properties linked to the same real estate group.In those cases, additions based on statements without adequate corroboration had been deleted.Following those decisions, it concluded that the addition against the man was not sustainable because the assessing officer had failed to substantiate the alleged payment with incriminating material.It therefore deleted the Rs 14.25 lakh addition.Tax experts said the ruling could affect several disputes arising from searches of real estate developers, particularly cases involving allegations of ‘on-money’ payments.According to them, the decision strengthens the position of taxpayers facing such additions. It also underscores that the income-tax department must establish, using credible evidence that can be independently verified, that a particular buyer paid cash beyond the declared sale consideration. Without such evidence, these additions could face difficulties in withstanding scrutiny at the appellate stage.